Washingtonpage 14

Place · 633 articles
Share

Coverage, page 14

page 14 of 32

US diesel prices hit new record high as Trump seeks to blame Kyiv

Average diesel prices in the United States struck a record high of just under $6.27 a gallon Tuesday, pressuring President Donald Trump ahead of midterm congressional elections. Diesel prices have soared as Washington's war with Iran disrupts the world's flow of fuel, though Trump has repeatedly downplayed the effects of the war, pinning the blame on Kyiv instead for its attacks on Russian oil refineries.

France 24France 24FRANCE2415 Sept

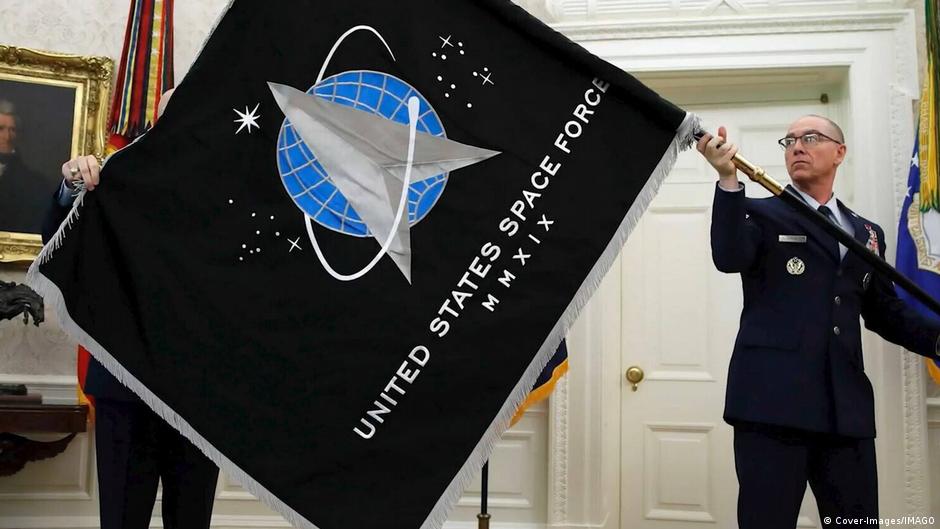
US confirms for first time it has deployed weapons into space

Analysts warn of an acceleration in high-risk arms race with Russia and China in Earth’s orbit The US has deployed weapons in space, the US military has confirmed, in an extraordinary public announcement that analysts warn will accelerate a high-risk arms race with Russia and China in Earth’s orbit. US secretary of the air force, Troy Meink, announced that Washington had active “on-orbit” weapons, meaning they had been deployed and were currently circling the globe. Continue reading...

The GuardianThe GuardianOliver Holmes15 Sept

Democrats say supreme court rejection of Trump mail ballot restrictions will ensure ‘safe, secure and accurate elections’ – US politics live

Comments come after court on Monday rejected the president’s mail ballot restrictions ahead of the November midterm elections Supreme court rejects Trump’s mail ballot restrictions for midterm elections Donald Trump is facing a rare backlash from the US Congress as Democrats and some Republicans push for guardrails on the world’s most powerful AI companies. Concerns over the dangerous potential of AI reached fever pitch this week after tech leaders sounded the alarm over the rapid advancement of the technology and its potential threat to humanity. Mitch McConnell , the 84-year-old former Senate majority leader from Kentucky, was seen in Washington for the first time in months on Monday, minutes before his office released a statement saying that he was back at work. With a slip of the tongue reminiscent of Joe Biden, Gavin Newsom , California’s Democratic governor, told CNN that he would not run for president in 2028 if his fellow Californian, former vice-president Kamala Harris , decides to run again, since “I know what that means: I know her base of supporters, I know her friends, the zen diagram on that is just pure crossover.” Donald Trump claimed there is a “SICK conspiracy” against artificial intelligence and data centers in response to the growing calls for greater checks on AI development. In a statement posted on social media , Barack Obama , the former US president, called for the pace of AI development to be slowed to allow time for the federal government to develop regulations to address “serious safety concerns”. Continue reading...

The GuardianThe GuardianTom Ambrose15 Sept

Will Record Copper Futures Trigger a Global Energy Crisis?

Macroeconomics and Economic Realities Copper futures recently hit historic highs across major global exchanges. COMEX contracts touched a record $6.894 per pound on September 10. London Metal Exchange three-month contracts reached a record $14,858.50 per metric ton the same morning. LME copper has climbed about 19% in 2026 and roughly 48% over twelve months. Hours after that peak, futures fell more than 4% on reports that Washington had not decided on refined copper tariffs. That reversal reveals two forces at work: a genuine structural deficit and a fragile tariff premium. Global mine output fell 1.1% during the first half of 2026. High interest rates and inflation complicate capital expenditure for major mining operators. Meanwhile, non-discretionary industrial demand continues to outpace physical extraction capacity. Geopolitics and Geostrategy Resource nationalism increasingly dominates international copper trade and supply chain dynamics. Major producing nations like Chile and the Democratic Republic of Congo tighten domestic regulations. Goldman Sachs estimates disruption could put 200,000 tonnes of Chilean and 125,000 tonnes of DRC output at risk this year; together, that equals roughly 1.4% of global mined supply. Furthermore, trade policy friction creates significant volatility in global inventory distribution. Washington imposed 50% tariffs on semi-finished copper products in July 2025, excluding refined cathode and concentrate. Commerce is reviewing whether a 15% refined copper tariff should begin in 2027, rising to 30% in 2028. Consequently, traders moved massive copper stockpiles into domestic American COMEX warehouses. LME stockpiles fell for 42 consecutive days, the longest run of declines since 2014. Sovereign nations now treat refined copper as a critical national security asset. High-Tech Industry Trends Electrification and artificial intelligence drive unprecedented demand for physical red metal. Artificial intelligence data centers require massive power distribution infrastructure and dedicated transformers. Engineering teams utilize thick copper busbars to deliver megawatts of electrical power. Thermal constraints prevent operators from substituting lower-cost aluminum in high-density facilities. Simultaneously, utility companies modernize electrical grids to connect utility-scale renewable energy assets. Wind and solar installations consume four to six times more copper per megawatt than legacy power plants. These converging high-tech trends guarantee sustained long-term consumption growth. Technology, Science, and Pharmaceuticals Copper plays a pivotal role across modern material science and medical technology. Advanced semiconductor manufacturing leverages high-purity copper interconnects to accelerate processing speeds. In pharmaceutical settings, copper's innate antimicrobial properties provide continuous biological surface protection. Medical facilities install specialized copper alloy surfaces to eliminate healthcare-associated pathogen transmission. Furthermore, high-performance computing clusters utilize copper cold plates to dissipate massive thermal heat load. Thus, copper remains an essential physical element bridging physical computing hardware and biological sciences. Business Models and Leadership Major mining corporations face a dramatic shift in commercial pricing power. Spot treatment and refining charges plummeted into negative territory for Asian metallurgical smelters. Miners now dictate terms to intermediate processors desperate to secure scarce raw concentrate. Freeport-McMoRan declared force majeure at its Grasberg operation and cut 2026 output guidance. Executive leadership across the sector prioritizes operational efficiency over aggressive output expansion. Mining executives cut non-essential capital spending while optimizing existing Tier-1 assets. Rising energy costs compound the pressure, since a 10% oil price increase lifts mining costs by 3.5%. Constrained shipping through the Strait of Hormuz keeps diesel and process inputs expensive. Custom smelters absorb the squeeze while low-cost extractors expand margins. Company Culture and Cybersecurity Modern mining operations embrace digital transformation and automated extraction technology. Autonomous haulage fleets and remote control rooms define modern company culture at Tier-1 mine sites. Engineers collaborate across international offices to monitor real-time pit operations and processing run rates. However, heavy reliance on connected internet-of-things sensors elevates severe industrial cybersecurity risks. Cybercriminals increasingly target critical infrastructure, automated conveyor systems, and remote refining controls. Mining leaders prioritize hardware-level cybersecurity encryption to safeguard physical operations and international supply chains. Patent Analysis and Future Outlook A detailed patent analysis highlights extensive corporate innovation in hydrometallurgy and solvent extraction. Leading miners hold valuable patents in heap leaching technologies and low-grade ore processing. Advanced processing patents enable extractors to recover valuable metal from previously unusable tailings. These proprietary chemical processes protect operating margins as natural ore grades decline globally. Will current copper futures records push industrial consumers past their financial breaking point? While the tariff premium may unwind, fundamental supply constraints ensure high long-term price floors. Copper remains the irreplaceable backbone of global electrification.

TITradingView Ideas15 Sept
Crude Oil (CL) Analysis, Key-Zones, Setup for Tue (Sep 15)

Bias: October WTI settled at 101.39, up 1.34 or 1.34 percent against Friday's 100.05, and that green number hides what was an outright rejection. The contract opened 102.25, ran to 104.95 during the European morning, then gave the whole advance back and settled in the lower fifth of a 4.42 dollar range, only 19.5 percent up from the 100.53 session low. This is the second consecutive session to attack the 104 handle and fail, after Friday printed 104.46, traded down to 98.48 and settled at 100.05. One difference matters: after the 02:30 PM ET settlement the market recovered and was holding 101.85 to 101.97 into the evening, so the session low was defended within an hour of being made, which Friday never managed. The driver was supply and geopolitics rather than demand. Press reports at 08:35 AM ET indicated a damaged Saudi pipeline will be largely out of service for three to five weeks, and the session high coincided with that headline. The reversal coincided with two statements out of Washington at 11:05 AM ET and 11:32 AM ET describing an energy-infrastructure understanding between Ukraine and Russia and openness to engagement with Iran, alongside official commentary that roughly 12 million barrels transited the Strait of Hormuz on Sunday. Iranian naval authorities publicly assert the strait is closed. Those claims cannot both be fully correct and the market is pricing the gap. The physical side remains genuinely tight: the curve is in steep backwardation with October roughly 4.4 above November and roughly 13.1 above January 2027, Brent settled 105.68 for a differential near 4.29, and computed product cracks sit at extreme levels, close to unchanged on the session once the different price bases are accounted for. The trend environment is powerful, with the 9-day directional index at 45.26 and every major average below spot, but the 14-day relative strength reading of 75.28 and a 14-day stochastic at 87.62 with the fast line rolling beneath the slow line describe extension. Bias is neutral with a downward lean beneath 102.29, favouring a fade of strength into proven supply rather than a chase, with the acknowledgement that a single overnight supply headline voids the technical case outright. Resistance: - 108.47, third pivot resistance, extended mechanical target reachable only on a discrete supply-shock session - 106.71, second pivot resistance, roughly 0.4 of one average true range beyond today's extreme and a plausible headline-day objective - 104.95, session high and October contract high, made on the largest half-hourly volume of the European morning and immediately rejected - 104.46, prior-week high, the upper edge of the three-session distribution band and the reference that defines whether the breakout attempt is live - 104.04 to 104.05, first pivot resistance in confluence with the September 10 breakout high one cent apart, the strongest single level on the chart - 103.00 to 103.15, round-number band and proven intraday supply, where three separate half-hourly attempts were rejected before the break - 102.29, Tuesday pivot point, the arithmetic centre of today's session and the first mechanical decision level Support: - 101.39, today's settlement, the level the post-settlement market has been defending into the evening - 100.53, session low made in the settlement window, the pivot on which the higher-low structure against Friday rests - 100.00 to 100.05, round number and Friday settlement within five cents of each other - 99.57 to 99.63, first pivot support in confluence with the 38.2 percent retracement of the September 8 to September 14 advance - 98.48, Friday's session low and the lower boundary of the three-session balance - 97.87, second pivot support, computed from today's high, low and settlement, with a full one-average-true-range decline landing lower at 97.36 - 96.05, the September 9 settlement and the price from which the current advance originated - 95.21 to 95.37, third pivot support in confluence with the September 10 breakout-session low, the deepest structural reference still relevant Primary Setup: SHORT October WTI from the 102.90 to 103.30 zone on a rejection of the round-number band during the pit session, stop 104.20 above the 104.04 to 104.05 pivot-resistance and prior-breakout-high confluence, which gives a 0.90 to 1.30 buffer appropriate to a 4.03 average true range. Targets at 101.39 first, today's settlement and the level buyers defended after the close was struck, 100.53 second at the session low and the structural pivot of the higher-low sequence, and 99.63 third at first pivot support in confluence with the 99.57 retracement, contingent on momentum extending through the round number on expanding volume. Risk to reward is roughly 1:1.6 to the first target and 1:3.2 to the third from a 103.10 entry midpoint against the 104.20 stop. Half size is appropriate, and this is a pit-session trade by design: the industry-group weekly inventory bulletin is scheduled at approximately 04:30 PM ET, two hours after the 02:30 PM ET pit close, so the day's largest scheduled repricing event arrives once pit liquidity has gone. Wednesday, September 16 then stacks the weekly petroleum status report at 10:30 AM ET against an interest rate decision at 02:00 PM ET and a press conference at 02:30 PM ET, which lands exactly at the pit close. The pit opens at 09:00 AM ET and the first directional test relative to 102.29 is the session's most informative signal. If the European bid instead carries through the pit open and 102.29 is accepted early, the fade is deferred rather than abandoned, and the reference flips to long from 102.20 to 102.45 on a retest of the reclaimed pivot, stop 101.25, targets 104.04 then 104.95. A settlement above 104.46 negates the short thesis entirely, and a confirmed disruption to Strait of Hormuz transit, further damage to producing or transit infrastructure, or a producer-group output statement would void it in real time regardless of price. Tuesday is a positioning session inside a defined structure rather than a decision session. The scheduled calendar is thin, with Chinese activity data at 10:00 PM ET Monday, the UK labour market report at 02:00 AM ET, German economic sentiment at 05:00 AM ET, the New York regional manufacturing survey at 08:30 AM ET expected at 15 against 20.60 prior, a twenty-year bond auction at 01:00 PM ET and a congressional cloture vote at 02:15 PM ET fifteen minutes ahead of the pit close. None of that moves crude on its own. What moves crude is unscheduled, and every geopolitical item that shaped today arrived outside a scheduled window, two of them after the pit close. Overnight gap exposure is larger in this contract than in any index, and the decision that deserves full conviction sits on the other side of Wednesday rather than inside Tuesday.

TITradingView Ideas15 Sept