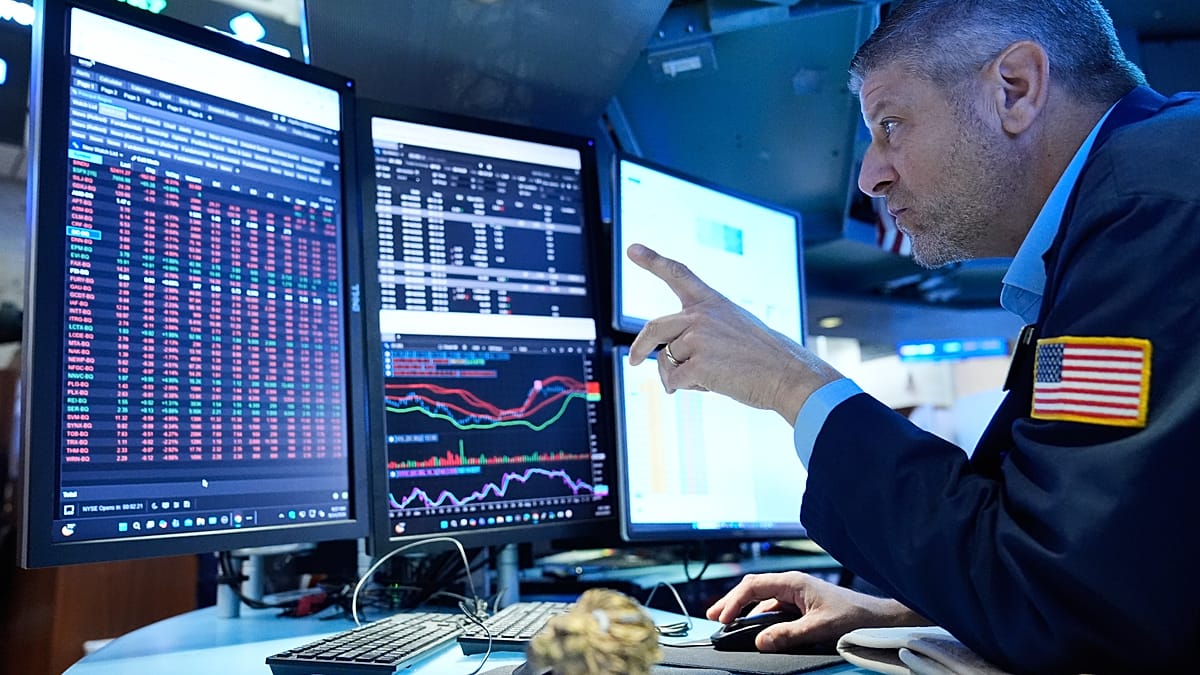
US 10-year Treasury yield breaches 5% as global bond sell-off deepens
The benchmark 10-year US Treasury yield briefly touched 5.011% on Monday, its highest level since October 2023, before retreating.
 Euronews15 Sept
The benchmark 10-year US Treasury yield briefly touched 5.011% on Monday, its highest level since October 2023, before retreating.
Euronews15 Sept
US Treasury yields have moved above 5%, yet USDJPY remains well below its July high. Earlier sharp declines were eventually recovered. The rebound after July stopped short of restoring the previous peak, and September brought another substantial decline. That combination makes USDJPY worth watching into this week’s Federal Reserve and Bank of Japan meetings. The question is whether the recent yen strength survives the announcements and begins to affect risk assets more broadly. Japanese equities already show a weaker structure, while Nasdaq provides a useful test outside Japan. For the broader stress thesis to develop, those markets need to do more than react to the same headline. They need to sustain the move after the initial volatility passes. THE CHANGE IN USDJPY https://www.tradingview.com/x/WsmZ8LPx/ The daily chart shows why the recovery matters as much as the initial decline. Several sharp selloffs earlier in the year were followed by substantial rebounds. Buyers eventually recovered the lost ground, and USDJPY went on to trade higher. The more recent sequence has been different. After the July peak, the pair fell sharply and recovered only part of the decline. The August rebound remained below that peak. September then produced another leg lower, leaving the current recovery beneath both earlier highs. This gives us an observable change: buyers have become less effective at repairing the damage after a selloff. A carry position typically combines borrowing in a lower-yielding currency with exposure to a higher-yielding asset. Its interest income accumulates gradually, while an adverse currency move can create losses quickly. A strengthening funding currency therefore becomes more consequential when it persists long enough to outweigh the income that made the position attractive. That mechanism offers one possible explanation for a weaker USDJPY recovery. The chart alone cannot establish how much carry exposure has been reduced or who is selling. It also cannot identify an intervention from the shape of a candle. Official intervention, changing policy expectations and position adjustment can all produce sharp moves. For this analysis, the useful evidence is what follows: whether buyers recover the decline, or whether the rebound fails and another lower low develops. THE RATES TEST https://www.tradingview.com/x/svufKuyg/ The US10Y snapshot shows yields above 5% and an upward trend into the event window. All else equal, higher US yields can support demand for dollar assets. USDJPY’s failure to return to its July high therefore deserves attention alongside that rates backdrop. There is an essential qualification. The US yield is only one side of the comparison. Japanese yields, expected policy paths and the maturity of the exposure all matter. The ten-year yield also contains inflation and term-premium components; it is not a direct measure of the short-term funding return available to a carry trader. A sustained USDJPY decline alongside falling US yields would be consistent with a reduction in the dollar’s rate advantage. A decline while US yields remain elevated would raise a more interesting question, but answering it would still require the Japanese side of the spread. This is why the response to the meetings matters. A policy decision can move short-term rate expectations and longer-dated bond yields differently. The useful test is whether the resulting rates environment helps USDJPY recover—and whether that recovery holds. THE JAPAN TEST https://www.tradingview.com/x/wnJju7JW/ The Nikkei chart has failed to recover its June peak. The August rally crossed the descending trendline, but it did not establish a lasting upward structure. Selling returned, and the index subsequently moved lower through a series of rebounds and renewed declines. That failed improvement is more informative than the trendline crossing itself. Buyers managed to change the appearance of the chart temporarily, but they did not regain control of the broader sequence. A stronger yen can affect Japanese equities through several channels. It can reduce the yen value of overseas earnings for some exporters, alter investment incentives and increase pressure on positions funded in yen. These effects vary across companies and portfolios, so yen appreciation does not translate mechanically into an index decline. The recent September lows provide the first practical test. If USDJPY weakens further while Japanese equities continue defending those lows, the currency move has yet to produce the equity deterioration required by this thesis. If the Nikkei breaks below them, attempts to recover the broken area and then turns lower again, the evidence becomes stronger. A subsequent move through the July low would extend that deterioration to a larger part of the chart. These are separate stages, and each needs its own confirmation. THE GLOBAL TEST https://www.tradingview.com/x/SXY6Vwx2/ Nasdaq tests whether the weakness is broadening beyond Japan. The chart here is the Pepperstone NAS100 cash CFD, so its session boundaries and gaps should be read on that basis. The recent opening gap and rebound attracted attention, but the gap itself does not establish a directional edge. The more useful observation is that the rebound has so far failed to restore the earlier September highs, leaving price back near the lower part of its recent structure. The next recovery matters. If buyers reclaim the breakdown area, establish a higher low and sustain the advance, Nasdaq would be absorbing the pressure. That would weaken the argument that the currency move is becoming a broader risk event. If rebounds continue to fail and the recent lows give way while USDJPY and the Nikkei are also weakening, the evidence for a wider adjustment increases. Even then, simultaneous declines would show participation across markets rather than prove a common funding cause. US equities can fall because of yields, earnings expectations or other developments independently of the yen. Evidence from positioning, credit and funding markets would be needed to make the stronger causal claim. WHAT WOULD CONFIRM IT The sequence begins with USDJPY sustaining its weakness beyond the initial central-bank reaction. A daily close below the September low shown in the snapshot would provide the first additional evidence. A recovery that fails to regain that broken area, followed by another lower low, would make the change more convincing. Japanese equities then need to participate. On the four-hour Nikkei chart, I would look for a close below the recent September lows and a subsequent failed recovery of that area. Nasdaq would provide the next layer if it also closes below its recent lows and fails to regain them on the rebound. These conditions distinguish a brief excursion through support from a market beginning to sustain lower prices. A single wick does not satisfy them, and a closing break remains provisional until the response becomes visible. The complete sequence would strengthen the case for a broader risk adjustment associated with persistent yen strength. It would still leave the scale and source of any forced position reduction open. WHAT WOULD INVALIDATE IT A sharp yen rally that is rapidly reversed would undermine the immediate event thesis. If USDJPY sweeps its September low, recovers it, establishes a higher low and breaks above the intervening rebound high, sellers would have failed to sustain the next leg. A sustained recovery above the August rebound high would challenge the larger sequence of weakening recoveries. That would be a more substantial structural reversal than one strong session after an announcement. The broader stress case also needs to be judged separately from the currency view. If the Nikkei recovers its recent September highs and Nasdaq repairs its breakdown while USDJPY remains soft, yen strength may persist without the equity transmission this post is testing. The W38 assessment belongs at Friday’s close, using the reference swings visible in these snapshots. If the breaks and failed recoveries have not developed by then, the weekly stress thesis remains unconfirmed. The observation window should not be extended simply to preserve the argument. THE LIMITS This is a framework for interpreting price reactions. No historical probability has been established here for this exact combination of USDJPY, yields and equity structures. The charts were captured on September 15. USDJPY is shown on the daily timeframe; the Nikkei and Nasdaq CFDs are shown on four-hour charts. Their session conventions differ, and the reference swings are those visible at the time of writing. US10Y does not establish the full US–Japan rate differential. Price action does not reveal the size of carry positions, and a stronger yen can coexist with resilient equities. The useful change so far is that USDJPY’s recoveries have become less complete. This week tests whether that behaviour persists—and whether the equity markets begin sustaining the same deterioration.

Looking at the outlook for gold prices over the next 15 days, market sentiment is shifting between bullish and bearish views. Some capital is beginning to position itself based on expectations of a Federal Reserve rate cut; a slight pullback in US Treasury yields is providing support for a gold price rebound. However, US inflation remains sticky, making a rapid rate-cut timeline unlikely. Consequently, the current rebound is merely a corrective move, and its sustainability remains to be seen; traders should remain alert to gold price volatility driven by fluctuations in the US Dollar Index. From a technical perspective, gold prices declined from the $4,301 level during the Asian trading session, dipping to a low near $4,283 before rebounding to a high of $4,318. The market has entered a phase of tug-of-war between bulls and bears ahead of the Federal Reserve's policy decision. The overall underlying trend remains bearish; this rebound is largely a technical correction and is unlikely to immediately reverse the prevailing trend. Rising energy prices are boosting inflation expectations and driving up both US Treasury yields and the US dollar, thereby exerting downward pressure on gold prices. Today's price action is likely to fluctuate within the $4,250–$4,350 range. My recommendations: SELL: Near $4,330 SELL: Near $4,345

The US dollar maintains its advantage ahead of the Fed meeting. Accelerating inflation and strong labor market data have convinced market participants of a high probability of an interest rate hike. Additional support for the US currency comes from the yield on 10-year US Treasury bonds, which remains near multi-year highs. The euro gains some support following the ECB's recent rate hike, but a significant part of this decision's effect is already reflected in quotes. At the same time, rising energy costs are worsening the economic prospects of the eurozone as a major fuel importer. This limits the European currency's ability to develop independent recovery against the dollar. In the current session, the divergence in the strength of short-term factors is crucial. The expectation of tighter Fed policy is supported by high yields and investors' cautious attitude towards risk, while support for the euro from the ECB is gradually weakening. Therefore, the fundamental scenario remains in favor of further EUR/USD decline. Trading idea: SELL 1.15400, SL 1.15700, TP 1.14700

📰 Fundamental News and Gold Price Action The USD and US Treasury yields are rising, putting pressure on Gold. US CPI data continues to indicate persistent inflation, leading the market to expect the Fed to maintain a cautious monetary policy stance. The FOMC meeting on September 16 is the most important upcoming event and could trigger significant volatility in XAUUSD. Although geopolitical tensions continue to support safe-haven demand, pressure from the USD and Treasury yields remains dominant for now. => Short-term fundamental outlook: Bearish bias on Gold. --- 📊 H1 Chart Analysis – Key Levels and EMAs 🔴 Key SELL Zone: 4,350–4,365 I consider this the most attractive Sell zone on the current chart because: * This is a supply zone that has triggered multiple price reactions. * The EMA34, EMA50, and bearish market structure are converging around this area. * Price continues to form Lower Highs on the chart. If price retraces to 4,350–4,365 but fails to break above this zone, it is highly likely to be just a pullback before another bearish move. Notably, this zone is also consistent with the 4,350–4,368 supply area that several recent H1 analyses are monitoring. => This remains my preferred SELL zone. 🔴 Closer SELL Zone: 4,325–4,335 Price is currently trading around 4,306, just below this zone. The problem is that the distance is relatively small. If price retraces toward: 4,325 → 4,335 and an H1 or M15 rejection candle forms, this could present an opportunity for a short-term Sell trade. However, I consider this zone less attractive than 4,350–4,365 because: * The entry is close to the current price, increasing the risk of being stopped out by a liquidity sweep. * The risk-to-reward ratio may not be favorable if the stop-loss is placed above 4,350. Some market analyses also identify 4,325–4,335 as an important short-term support/resistance zone. ⚪ Zone: 4,265–4,250 This zone is currently not safe for an immediate Buy or Sell entry. Reason: Price has already made a strong bearish move into this area before bouncing. If price continues to decline toward this zone, we should not immediately BUY simply because price reaches the level. It would be better to wait for: * A liquidity sweep of the lows; * A strong rejection wick; * A bullish engulfing candle; * Or an M15/H1 market structure shift toward a **Higher Low**. If confirmation appears, a Buy scalp could be considered. If an H1 candle closes below 4,255–4,260, this gray zone would be invalidated, potentially opening the door to a deeper bearish move. --- 📝 Summary The H1 structure remains Bearish, characterized by Lower Highs and Lower Lows. The upward move from 4,260–4,280 currently appears to be a technical retracement rather than a confirmed trend reversal. The preferred strategy is to wait for price to retrace into resistance before looking for SELL entries, rather than chasing Sell positions at the lows. BUY setups should only be considered if price breaks through key resistance levels and forms a Higher High + Higher Low structure. => H1 Bias: Bearish — Prefer SELL on pullbacks.

The sanctions on VTB Bank highlight the increasing complexity and permanence of US financial restrictions, impacting global compliance and diplomacy.
 CryptoBriefing•Editorial Team14 Sept

Rising US Treasury yields could strain borrowers, elevate government debt costs, and challenge fixed-income portfolios amid persistent inflation.
CryptoBriefing•Editorial Team14 Sept
US Treasury 3-month and 6-month bill auctions cleared at higher yields, with the 26-week bill attracting stronger demand as investors chase
CryptoBriefing•Editorial Team14 Sept
The sanctions could severely disrupt Iran's aviation sector, strain international relations, and impact global aerospace supply chains.
CryptoBriefing•Editorial Team11 Sept
Rising Treasury yields signal increased borrowing costs, potentially slowing economic growth and impacting consumer spending and investment.
CryptoBriefing•Estefano Gomez11 Sept
US Treasury secretary’s claims of insider knowledge could erode market perceptions of Japanese central bank’s independence

The Treasury's limited buyback highlights the disconnect between government actions and market expectations, risking increased market volatility.
CryptoBriefing•Editorial Team10 Sept
Increased foreign demand for US Treasury bonds suggests strong global confidence in US debt, potentially stabilizing long-term interest rates.
CryptoBriefing•Editorial Team10 Sept
Rising 30-year Treasury yields could increase borrowing costs, impact mortgage rates, and pressure equity valuations, affecting economic growth.
CryptoBriefing•Editorial Team10 Sept
Rising Treasury yields signal a tighter monetary environment, reducing the likelihood of the Fed pausing interest rate hikes soon.
CryptoBriefing•Estefano Gomez10 Sept
Bitcoin Magazine US Treasury Secretary Scott Bessent ‘Strongly Urges’ Senate To Pass Clarity Act Senators will vote on the long-awaited crypto Clarity Act next week. This post US Treasury Secretary Scott Bessent ‘Strongly Urges’ Senate To Pass Clarity Act first appeared on Bitcoin Magazine and is written by Mathew Di Salvo .

Bessent's challenge could destabilize global markets, impacting carry trades and signaling potential shifts in US-Japan economic strategies.
CryptoBriefing•Editorial Team9 Sept
The expanded buyback program may stabilize liquidity but risks market disappointment if expectations for larger operations aren't met.
CryptoBriefing•Editorial Team9 Sept
The Treasury's buyback expansion highlights ongoing challenges in managing national debt and liquidity, impacting broader economic stability.
CryptoBriefing•Editorial Team9 Sept
The intensified sanctions could disrupt global aviation logistics, increase compliance costs, and strain US-Iran diplomatic relations further.
CryptoBriefing•Editorial Team8 Sept